Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
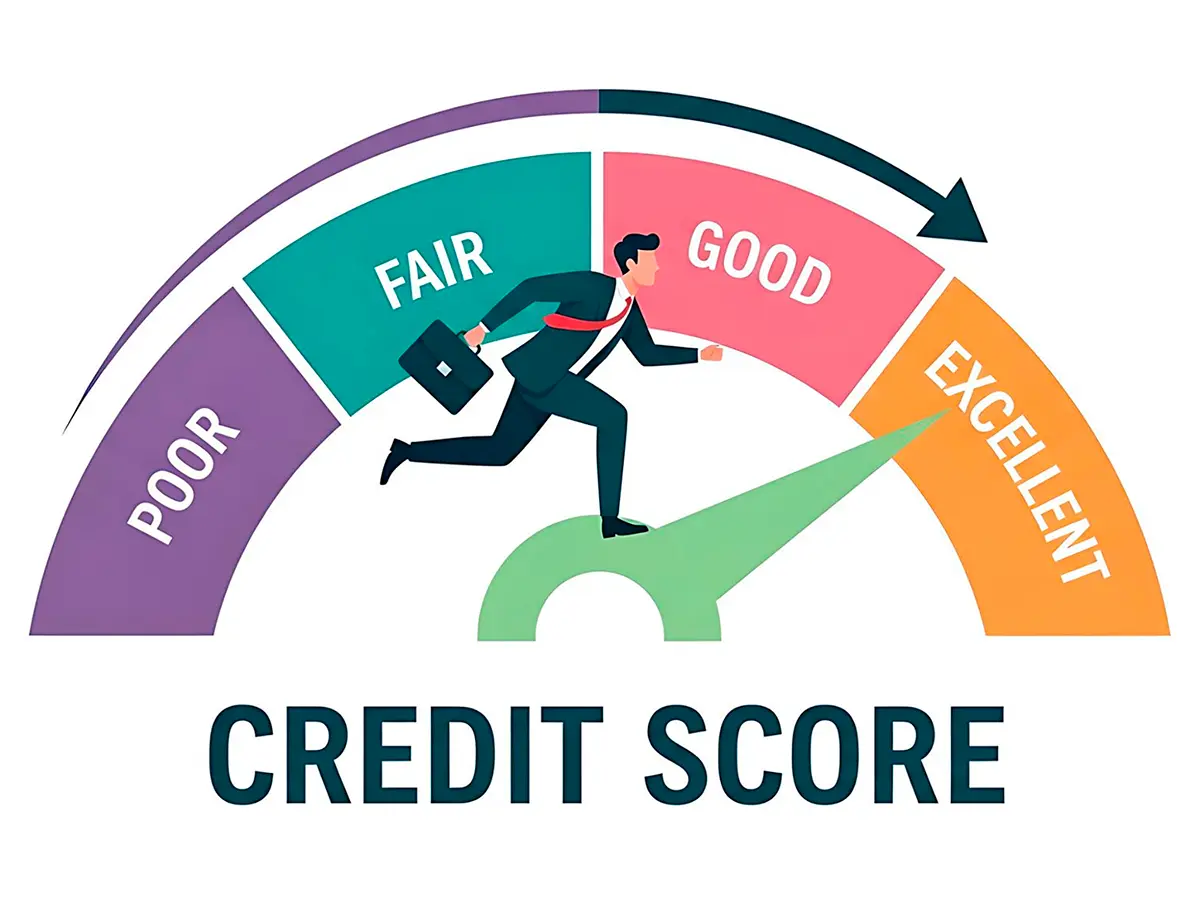
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
credit score instant boost: advanced moves that favor selection and stability
What "instant" really means
Scores don't change on a button press; they update when data reporters refresh your file. Yet we can trigger faster improvements by aligning actions with reporting cycles or by working with a lender that can request a rapid rescore. Our focus: short-cycle wins that don't jeopardize long-term stability.
Fast levers that respect stability
Utilization choreography
We target how much of each revolving limit reports as used. Dropping utilization can yield points quickly once the next statement hits. Selection matters: we don't pay everything blindly; we prioritize balances that report soon or sit over key thresholds.
- Hit the thresholds: Move from above 30% to below 30%, then below 10% where feasible. Each step can matter.
- Card-by-card, not just total: A single maxed card can hurt even if overall utilization looks fine. Lower the outliers first.
- Pre-statement payments: Pay before the statement closing date so the lower balance is what gets reported, not just before the due date.
- AZEO, carefully: Many see gains with All Zero Except One small balance reporting. Keep the lone balance under 10% of that card's limit to show active use without debt.
- Soft-pull limit increases: If your issuer offers a no-hard-pull increase, a higher limit lowers utilization instantly once posted. Avoid hard pulls if you're near an application.
File accuracy and thoughtful data additions
Accuracy is stability. We dispute clear errors only - misreported late payments, duplicate accounts, or a paid collection still marked open. For thin files, selectively add positive history: rent and eligible utility payments can create or thicken tradelines. We add only data that's consistently on-time and likely to continue, avoiding anything that could introduce volatility.
Application timing and inquiry hygiene
We pause new accounts when chasing an instant lift. Group rate-shopping for auto or mortgage within a tight window so inquiries are treated as one. We don't close old cards before applying; age and depth reinforce stability.
A small real-world moment
Last spring, we noticed a card sitting at 51% utilization days before a mortgage pre-approval. We sent a mid-cycle payment that dropped it to 8% two days before the statement cut. The next refresh showed an 18-point lift - just enough to nudge us into a better pricing tier, and the payment fit our cash flow plan.
Checklist to guide selection now
- List statement closing dates and pay high-utilization cards first, before they report.
- Target thresholds (30% → 10%); aim for one small balance and the rest at zero.
- Ask for soft-pull credit limit increases where your history is strong.
- Fix obvious errors; add only reliable rent/utility data you'll keep current.
- Defer new credit lines and keep your oldest accounts open.
Guardrails we keep
We don't chase points at the cost of liquidity. If paying down to a threshold strains cash, we scale back rather than risk a late payment. Stability beats spectacle.
With precise selection and steady routines, the "instant" part happens at the next update - and the gains tend to stick as our habits compound, leaving room for the next small refinement we choose to make.
How to Improve Your Credit Score - 1. Make On-Time Payments - 2. Pay Down Revolving Account Balances - 3. Don't Close Your Oldest Account - 4. Diversify the ...
On this video I go over 2 of the most powerful ways in how to raise your credit score in less than 24 hours. One will cost you absolutely ...
Looking to boost your credit score, even with bad credit? In this video, I'm sharing 10 powerful credit lines that can help you increase ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.